What "independent" actually means
Here's what to do, in 4 steps.
Filing for an independently entitled divorced-spouse benefit is mostly about your documents — not your ex. SSA does the records work behind the scenes. Here's the actual sequence I'd follow.
-
Gather your divorce decree and marriage certificate
Independent-entitlement claims rest on your documents, not your ex's cooperation. Pull the certified final divorce decree (showing the date the divorce became final) and the original marriage certificate. SSA will use these to confirm both the 10-year marriage and the 2-year-final-divorce conditions.
Time: 20 minutes Cost: Free
-
File at ssa.gov/apply or by phone
You can start the application online at ssa.gov/apply or by calling 1-800-772-1213. Tell SSA you're filing as a divorced spouse on your ex's record — they'll route the claim correctly. You'll need your ex's full legal name, date of birth, and Social Security number if you have it; if not, SSA can usually locate the record from name and DOB.
Time: 15-30 minutes Cost: Free SSA application portal
-
Expect SSA to verify your ex's record internally
This is the part that surprises people. SSA matches your ex's record by Social Security number and confirms their age and insured status without contacting them. Your ex doesn't get a notice, doesn't have to sign anything, and doesn't have to be on speaking terms with you. Processing typically takes a few weeks; complex cases take longer.
Time: Days to weeks Cost: Free POMS RS 00202.005 — Divorced Spouse
-
Once approved, treat your check as independent
After approval, your monthly benefit operates on its own track. If your ex later files, suspends, or withdraws their own retirement claim, your divorced-spouse check generally keeps coming the same way. The one big exception: if your ex passes away, you may convert to surviving-divorced-spouse benefits — often a higher amount — so notify SSA promptly when that happens.
Time: Ongoing Cost: Free
Which of these sounds more like you?
I've watched people hold off filing because they thought they needed their ex to act first. They didn't. Here's how the independence really works in the situations I see most often.
I just cleared the 2-year wait10-year marriage; ex is at least 62; you're not currently married
Once you've crossed the 2-year mark since the divorce became final, your independent-entitlement claim is ready to file. Your ex doesn't need to know, doesn't need to file, doesn't need to do anything. Bring your divorce decree, marriage certificate, and your own ID; SSA does the rest internally.
You can file the month before you want benefits to start. If you file at or after FRA, you may also be able to claim up to 6 months of retroactive benefits per POMS GN 00204.030 — ask the claims rep about it.
My ex filed after I didAlready collecting; ex files later
Your check stays the same. The whole point of independent entitlement is that your benefit is computed on your ex's primary insurance amount (PIA) regardless of whether the ex has filed yet. SSA already locked in the PIA when they verified your claim.
If your ex files for their own retirement after you, neither benefit changes the other. Your monthly amount keeps coming on the same schedule.
My ex suspended their benefitVoluntary suspension by NH
Voluntary suspension by your ex generally does not affect a divorced-spouse benefit that's already in pay on an independent-entitlement basis. The 2015 Bipartisan Budget Act closed off file-and-suspend for new auxiliaries on the same record — but the rule for independently entitled divorced spouses is treated separately, and most existing claims continue.
Edge cases exist (date of suspension, who filed first, whether you were dually entitled). If yours feels complicated, call SSA before assuming anything.
My ex withdrew their claimWithdrawal of NH application
If your ex withdraws their own retirement claim (POMS GN 00206 family), the question is whether you were entitled as a regular divorced spouse on their filed claim, or independently. Independent entitlement is yours — it doesn't depend on the ex's claim staying open. So in the typical independent-entitlement scenario, your benefit continues.
If you were drawing as a regular divorced spouse because your ex had filed, the analysis is different and you may be affected. Verify with SSA before changing anything on your end.
Can I get back-pay for the wait?Retroactive months at FRA
If you file at or after your full retirement age, SSA may pay up to 6 months of retroactive benefits — but not earlier than the month you reached FRA (POMS GN 00204.030B.2). If you file before FRA, the rule is different: no retroactivity for reduced benefits. Your first month of entitlement is the month you elect at filing.
This is the same retroactive rule that applies to regular retirement claims. The 2-year divorce-finality wait isn't bridged by retroactivity — you can't go back before the 2-year mark.
My ex passed away after I filedConversion to surviving-divorced-spouse
When your ex passes away, you may qualify to convert from divorced-spouse benefits to surviving-divorced-spouse benefits — which are generally higher (up to 100% of your ex's PIA versus 50% as a divorced spouse). The conversion isn't automatic; you have to notify SSA and file for the survivor benefit.
Report the death promptly and ask SSA to evaluate survivor entitlement. The 10-year marriage rule still has to be met (same rule as the divorced-spouse claim), and the unmarried-or-remarried-after-60 rule applies for the survivor side.
I'm helping a parent navigate thisAdult child or caregiver
Most adult kids I work with are surprised at how independent the rule actually is. Your parent doesn't need to contact their ex. SSA does the records check on their end. The file you'll need is straightforward: certified final divorce decree, marriage certificate, your parent's ID and Social Security number.
If you'll be doing the legwork, file SSA-1696 to be appointed as their representative. That gives you authority to talk to SSA on their behalf and receive notices. If your parent uses a my Social Security account, pull the benefits estimate first — it'll show divorced-spouse versus their own record so you can compare.
I haven't cleared the 2-year waitRecently divorced; ex hasn't filed
Independent entitlement requires that the divorce has been final for at least 2 continuous years. If you haven't crossed that mark and your ex hasn't filed for their own retirement, you can't file as an independently entitled divorced spouse yet — the 2-year clock has to run first.
There's a separate page that walks through exactly when the clock starts, what counts as "final," and what to do if your ex files first (which can let you skip the wait). That's the page to read next.
Still inside the 2-year window after divorce? → Read: Divorced-spouse 2-year rule
Everything people ask me
What does "independent entitlement" actually mean?
It's the SSA term for the rule that lets you collect divorced-spouse benefits on your ex's earnings record without your ex having to file for their own retirement. POMS RS 00202.005B.2 spells out the conditions: 10-year marriage, 2-year-final-divorce, ex is at least 62, you're unmarried, and your own retirement benefit (if any) is less than half your ex's PIA. Once those are met, your claim operates independently of your ex's filing decisions.
Do I need my ex to cooperate or sign anything?
No. The whole point of independent entitlement is that you can file without your ex's cooperation, signature, or knowledge. SSA does the records work internally — they pull your ex's earnings record by Social Security number, confirm age and insured status, and proceed. Bring your divorce decree, marriage certificate, and your own ID; that's the file SSA needs from you.
Does my ex find out when I file?
Generally no — SSA does not send your ex a notice when you file an independently entitled divorced-spouse claim. Your benefit doesn't reduce theirs (a divorced-spouse benefit doesn't take anything from the ex's own retirement check), so SSA has no operational reason to involve them. The agency treats the records check as internal.
If my ex files later, does my benefit change?
No. Your divorced-spouse benefit was computed on your ex's primary insurance amount when you filed, and that PIA doesn't change just because the ex files later for their own retirement. Independent entitlement means the two checks operate on parallel tracks — neither one moves the other.
If my ex suspends or withdraws their claim, does my benefit change?
Generally no — if you're independently entitled, your benefit doesn't depend on your ex's claim staying open. Voluntary suspension by the number-holder typically does not affect a divorced-spouse benefit on independent entitlement. Withdrawal of the ex's own claim is a more nuanced area; if you got drawn in as a regular divorced spouse on the ex's claim, the analysis differs. When in doubt, call SSA before assuming anything.
Can I get retroactive benefits to cover the 2-year wait?
No — retroactivity doesn't bridge the 2-year-final-divorce window. Per POMS GN 00204.030, RIB and divorced-spouse claims filed at or after FRA can get up to 6 months of retroactive benefits, but never earlier than your FRA month and never before you actually met all entitlement conditions (including the 2-year mark). If you file before FRA, there's no retroactivity for reduced benefits at all.
What if my ex passes away after I'm already collecting?
You may qualify to convert from divorced-spouse benefits to surviving-divorced-spouse benefits, which are typically higher (up to 100% of your ex's PIA, versus 50% on a divorced-spouse claim). It's not automatic — notify SSA promptly, and ask them to evaluate survivor entitlement. The 10-year marriage rule still has to be met, and there are separate marriage rules on the survivor side.
Does the 2-year rule apply if my ex has already filed?
No. The 2-year-final-divorce rule is specific to independent entitlement — it's the gate for filing when your ex has not filed. If your ex is already collecting their own retirement, you can file as a regular divorced spouse without waiting two years (you still need the 10-year marriage and you still need to be at least 62 yourself). The companion page on the 2-year rule covers this distinction in detail.
How long does SSA take to approve an independent-entitlement claim?
Most are processed in a few weeks once your application is in. Independent-entitlement claims sometimes take a bit longer than a straightforward retirement claim because SSA has to pull and verify the ex's earnings record on its end — but it's still routine work for them. If yours is taking longer than a couple of months, call your local SSA office or the national line.
Where in the law is independent entitlement?
Statutory basis is 42 USC § 402(b)(4) (divorced wife) and 42 USC § 402(c)(4) (divorced husband). Operationally, SSA's POMS RS 00202.005B.2 lays out the rule: the number-holder must be at least 62 throughout the first month of entitlement but "need not have filed a claim for benefits." That phrase is the heart of independent entitlement.
More help with this topic
Use the related guide for more detail and practical next steps.
Sources
References from this article's earlier edition are listed below with their original dates. Check the linked agency for current rules and amounts.
- Independent entitlement allows divorced-spouse benefits to be paid even when the number-holder (ex) has not filed for their own retirement, provided the NH is at least 62 throughout the first month of … —secure.ssa.gov(verified 2026-04-27)
- Independent entitlement requires the divorce to be final for at least 2 continuous years. —secure.ssa.gov(verified 2026-04-27)
- The number-holder (ex) must be 62 throughout the first month of the divorced-spouse claimant's entitlement. The ex does not need to have filed a claim. —secure.ssa.gov(verified 2026-04-27)
- RIB applications filed at or after FRA can receive up to 6 months of retroactive benefits, but never earlier than the month of FRA attainment. —secure.ssa.gov(verified 2026-04-27)
- Reduced RIB benefits filed before FRA do not allow retroactivity. The first possible date of payment is the date of application or protective filing. —secure.ssa.gov(verified 2026-04-27)
- P.L. 101-508 § 5116 (effective January 1, 1991) eliminated retroactive reduced benefits when the NH files for retirement and an unreduced auxiliary is entitled — except for an independently entitled … —secure.ssa.gov(verified 2026-04-27)
- Voluntary suspension of the number-holder's own benefit generally does not affect a divorced-spouse benefit paid on an independent-entitlement basis. SSA's published rule states that when an NH … —ssa.gov(verified 2026-05-07)
- Withdrawal of the number-holder's own retirement claim is governed by POMS GN 00206. Effect on a divorced-spouse claim depends on whether the divorced spouse was independently entitled or entitled on … —secure.ssa.gov(verified 2026-04-29)
- A divorced-spouse benefit is up to 50% of the number-holder's primary insurance amount when the divorced spouse files at full retirement age. —ssa.gov(verified 2026-04-27)
- If the divorced spouse files at age 62 with FRA of 67, the divorced-spouse benefit is reduced to approximately 32.5% of the NH's PIA. —ssa.gov(verified 2026-04-27)
- A divorced-spouse benefit caps at 50% of the number-holder's PIA when the divorced spouse files at full retirement age. Delayed Retirement Credits do not apply to spousal or divorced-spouse benefits — … —secure.ssa.gov(verified 2026-05-07)
- The divorced-spouse claimant must have been married to the NH for at least 10 years immediately before the divorce became final. —secure.ssa.gov(verified 2026-04-27)
- The divorced-spouse claimant must be unmarried at the time of filing (with limited exceptions for remarriage to certain Social Security beneficiaries). —secure.ssa.gov(verified 2026-04-27)
- The statutory basis for the independently-entitled-divorced-wife rule is 42 USC § 402(b)(4). —law.cornell.edu(verified 2026-04-29)
- The statutory basis for the independently-entitled-divorced-husband rule is 42 USC § 402(c)(4). —law.cornell.edu(verified 2026-04-29)
A useful next step
Open the guide page for Dr. Ed's explanation and practical next steps.
Read Dr. Ed's guide: Social Security for Spouses, Ex-Spouses and Survivors
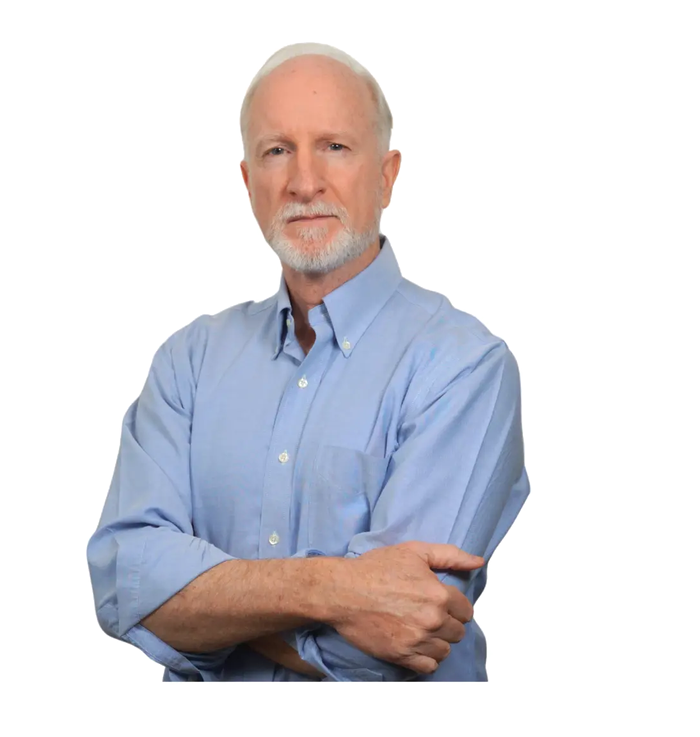
About Dr. Ed Weir
Dr. Ed Weir, PhD, spent over 20 years as a Social Security Administration District Manager and over 30 years in government service. He watched good people lose benefits they'd earned every single day because nobody told them the rules. Over $30 billion in benefits goes unclaimed every year. He built 24Help.org to change that.
Trusted by over 2 million Americans every month · 4.5M+ YouTube views monthly · 160,000+ Facebook community members